
decision.ezee
Accelerate Approvals with AI-Powered
No-Code Credit Decisioning Software.
Launch in Weeks.
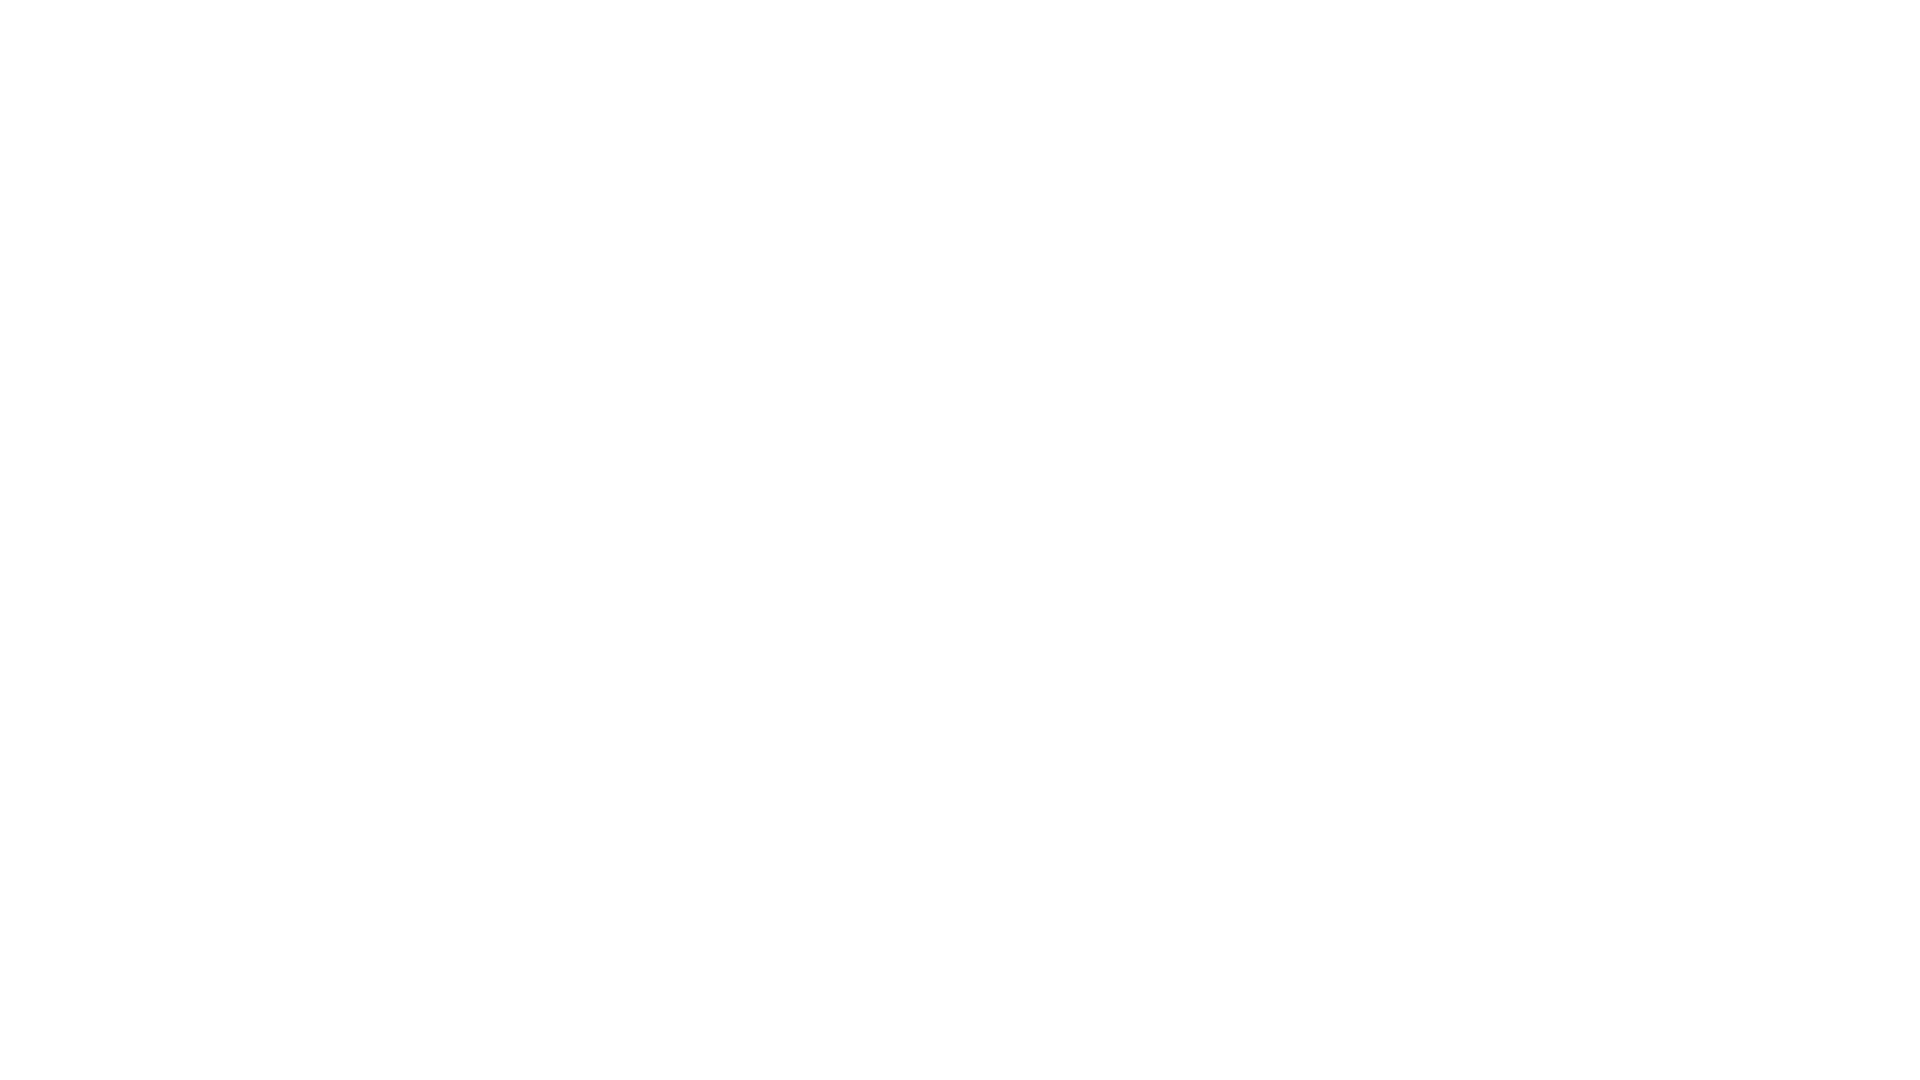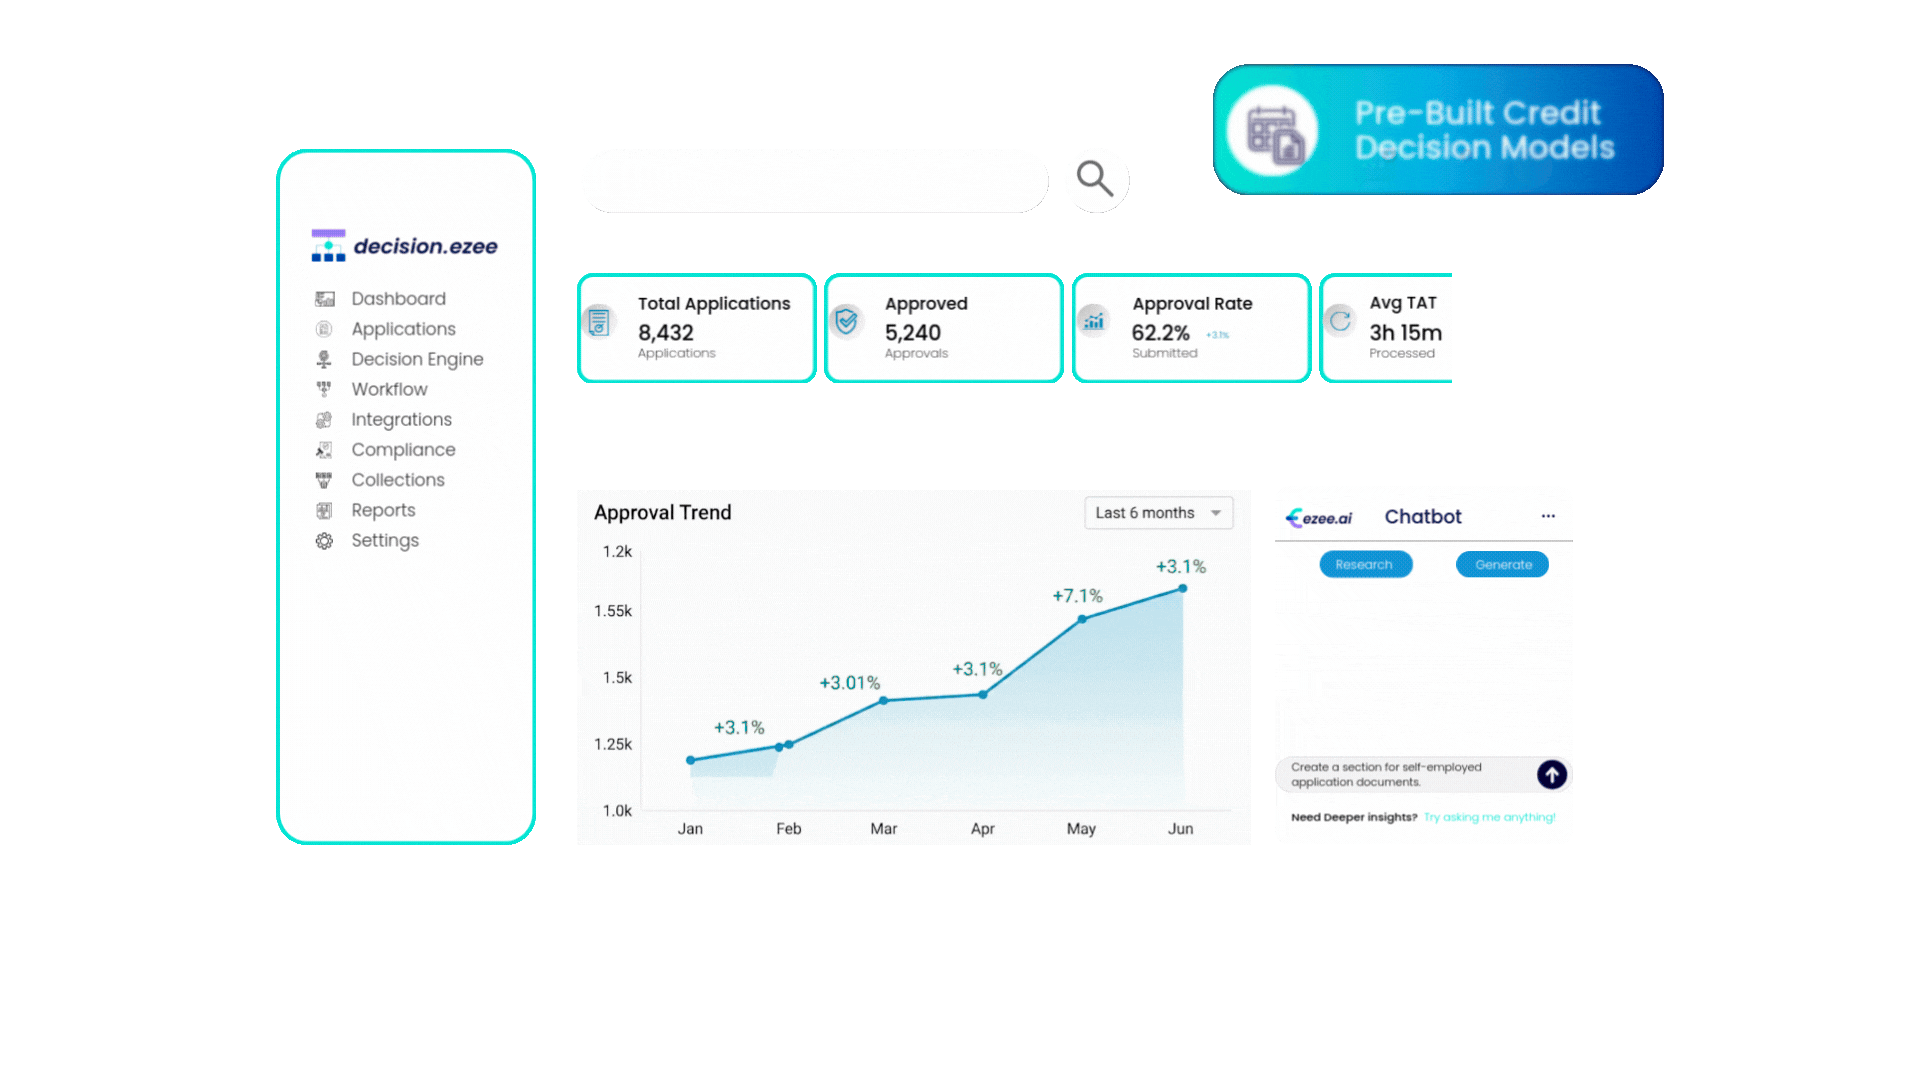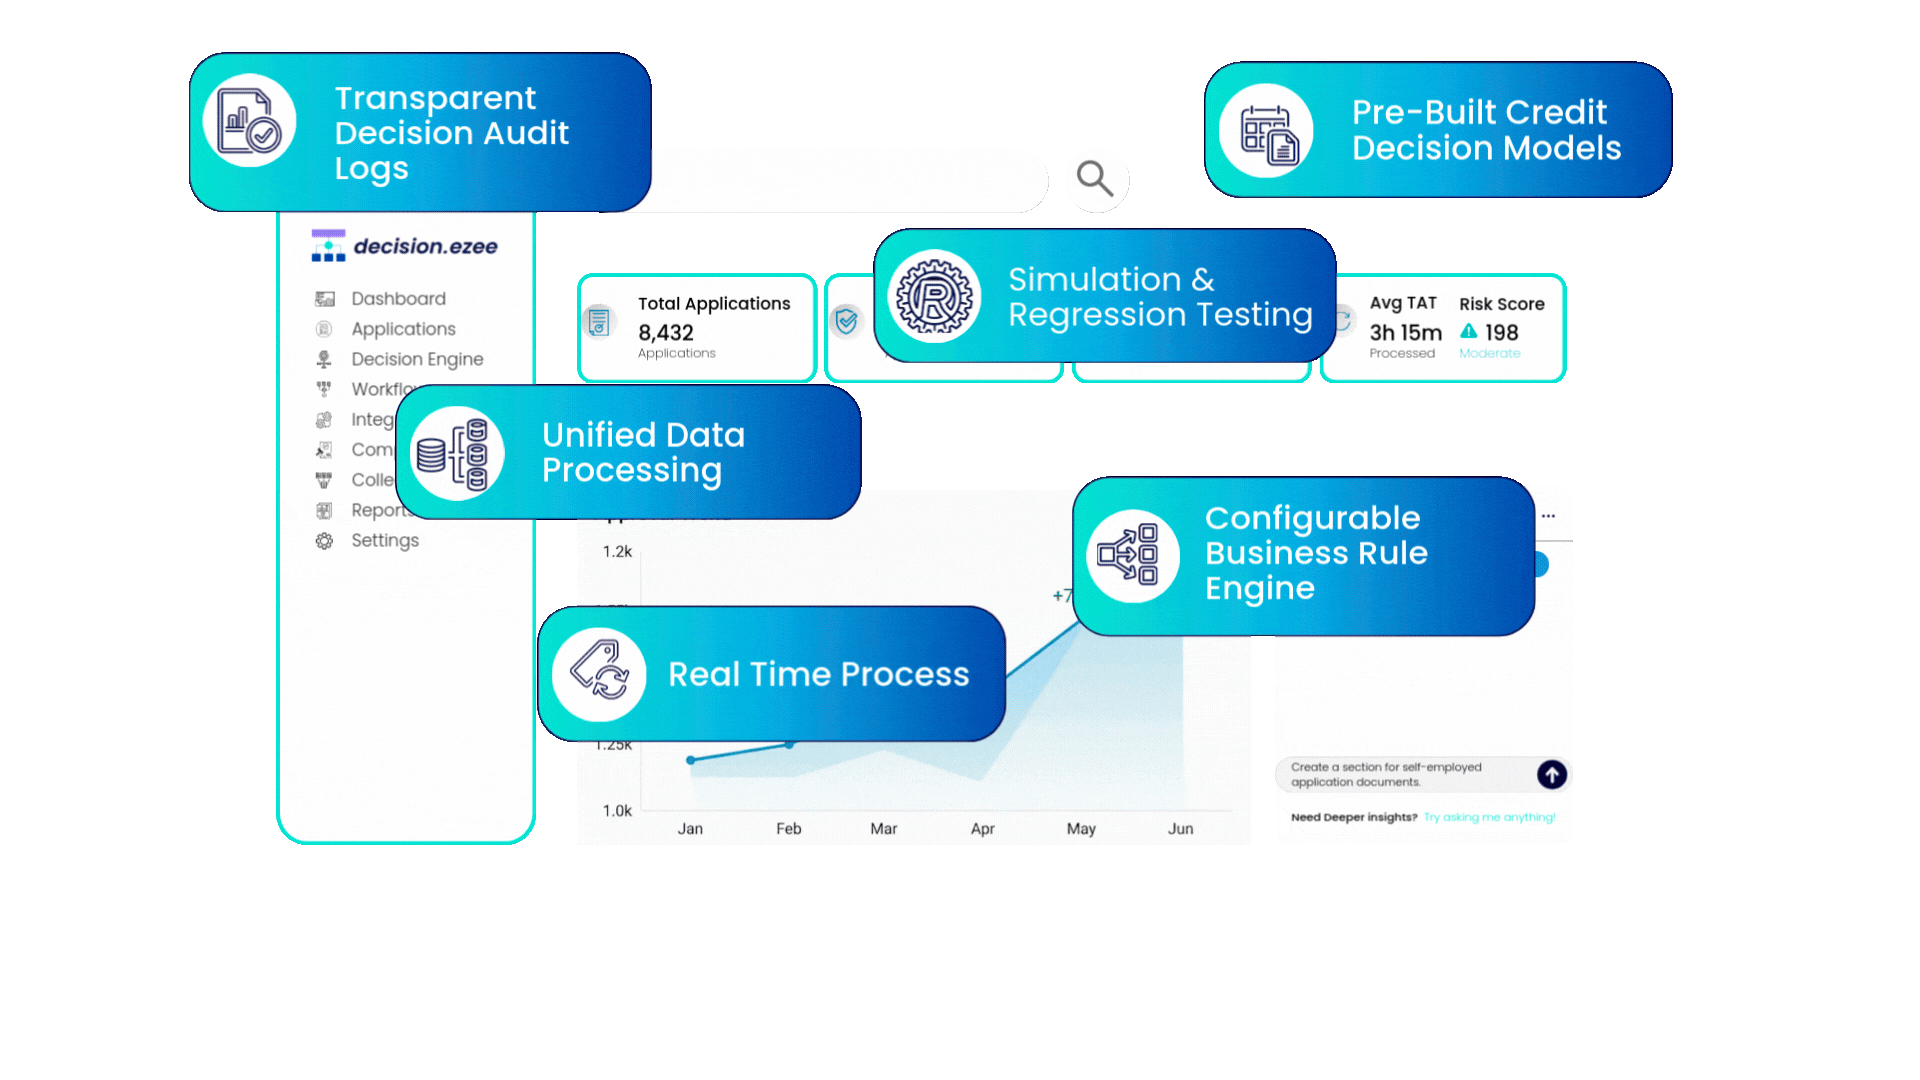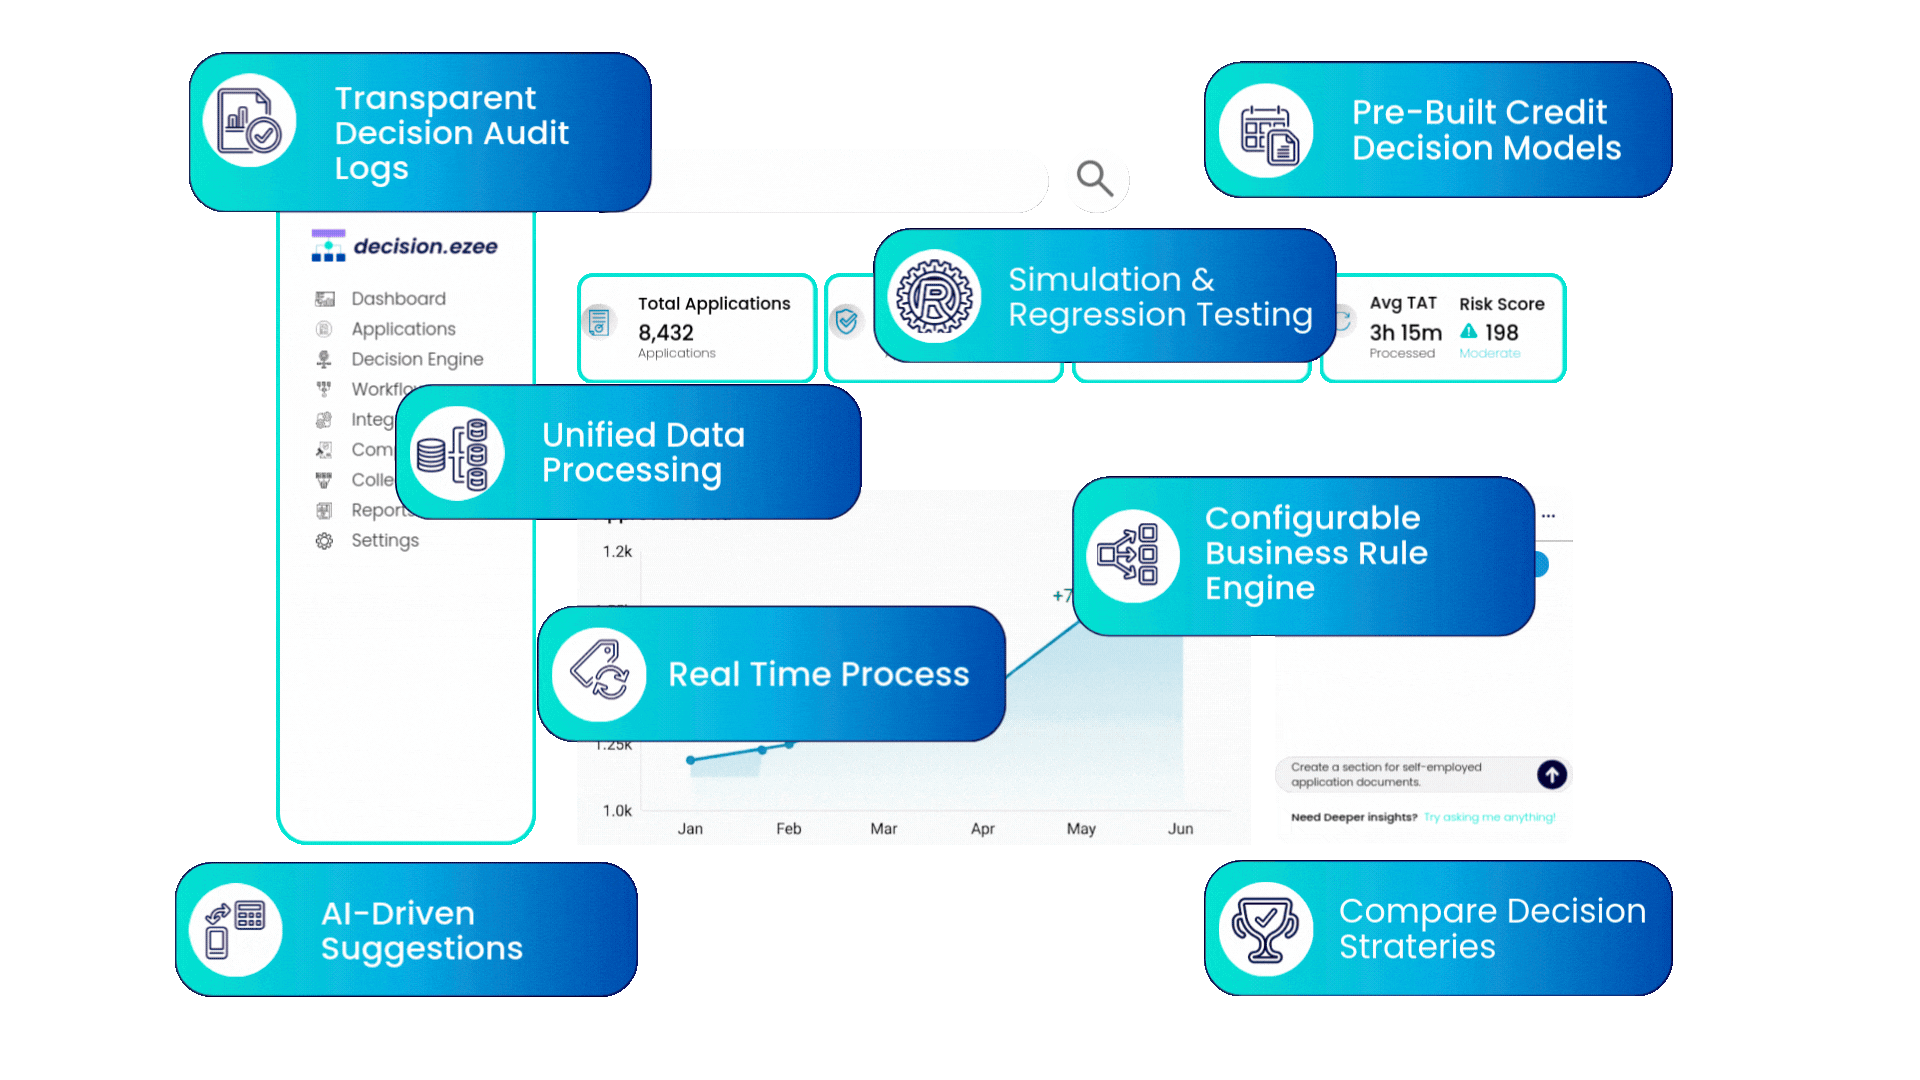
Configure credit policies, build decision flows and automate lending decisions without code. Empower credit and risk teams to test, refine and deploy decision logic while maintaining control, consistency and traceability.
Built for Every Role That Owns the Credit Stack
decision.ezee empowers the teams responsible for
credit decisions, risk management, technology and business growth.

Chief Risk Officers
Maintain consistent credit policies with explainable, traceable and auditable decisions.

Heads of Credit & Product
Configure and launch scoring, eligibility and pricing policies without depending on development cycles.

CIOs & CTOs
Integrate decision workflows through API-first architecture, JSON-based interfaces and webhooks.

CEOs & Business Heads
Accelerate lending decisions, improve operational efficiency and strengthen portfolio performance.
From Rule Authoring to Live API In One Screen
Watch how a credit policy moves from configuration to a live, callable API endpoint with no code, no dev ticket.


Author, Test, and Deploy
Credit Rules Without Code

AI Rule Authoring Studio
Build configurable credit rules and eligibility policies visually.

AI Scorecard Builder
Create and deploy scorecards using configurable risk indicators.

Decision Flow Orchestration
Orchestrate rules, scorecards and decision workflows.

Decision Tables & Grids
Configure pricing, fees and risk-based decision tables.

Expressions & Formula Engine
Automate EMI, FOIR, DTI and complex calculations.

Data Source Marketplace
Connect credit bureaus and external data providers.
Full Control, Traceability,
& Compliance.

Testing & Simulation
Simulate credit decisions & validate rules before deployment.

Analytics & Monitoring
Process large volumes of credit decisions efficiently.

Maker-Checker Governance
Track decision outcomes, performance & execution metrics.

Bulk & Batch Execution
Integrate decision workflows with external lending systems.

API-First Architecture
Manage policy approvals with role-based controls.

Conversational AI Decisioning
Interact with decision logic using natural language.


Your Rules Get Sharper with
Every Decision Cycle

AI Live Policy Execution via MCP
Execute & interact with governed credit policies through MCP.

AI Compliance & Audit Trail
Maintain traceable records of decisions and policy execution.

AI Multi-Agent Consistency
Coordinate AI agents to deliver decisioning outcomes.
AI Bidirectional Learning
Use outcomes & feedback to improve recommendations.

AI Context-Aware Decisioning
Apply relevant borrower context to decision workflows.

AI-Powered Rule Recommendations
Get AI-assisted suggestions to refine credit rules and policies.
10 Ways Institutions Turn
decision.ezee into Their Muscle
Each runs in production across banks, NBFCs, credit unions, and fintechs globally.
Credit & Risk

Loan Eligibility Rules
Filter by age, income, & score; auto-reject or route instantly.

Credit Scorecards
Score risk using bureau, banking, and behavioural signals.

Fraud Detection
Flag document, geo-IP, and velocity anomalies instantly.

Underwriting Flows
Orchestrate knockouts, scoring, verification, and decisions.

Compliance Checks
Enforce regulations and flag gaps before go-live.


Automation & Ops

Interest Rate Slabs
Risk-based pricing tables, Excel-compatible.

EMI & Serviceability
Calculate EMI and assess FOIR, DTI and LTV.

Product Recommendation
Best-fit product matching by profile and eligibility.

Incentive & Payouts
Automate commission calculations and DSA payouts.

Pre-Approved Offers
Generate offers using borrower behaviour and repayment history.
Enterprise Security & Compliance
Meeting the most stringent regulatory requirements while enabling innovation

ISO 27001:2022

SOC 2 Type II

AES-256

GDPR Ready

RBAC

SaaS

Cloud
On-Prem
Hybrid
While You Evaluate, Competitors Accelerate
Proven at scale across 3 continents
Trusted by 55+ Banks & NBFCs Across Segments


9 of 28 Regional Rural Bankss in India Run on ezee.ai


Built for Your Growth, Not Just
Your Current Size
Scalable Decision Execution
Handle millions of credit decision executions monthly.
Multi-Lender, Multi-Tenant Architecture
Support multiple lenders with isolated environments and configurations.
Launch 3x More Products per Quarter
Configure and launch new lending products with greater speed.
Legacy BRE vs. decision.ezee
Where traditional rule engines fall short and what changes with AI-native, no-code.
| Capability | Legacy / Traditional BRE |

|
|---|---|---|
| Rule Authoring | Code-heavy, IT-dependent | No-code, AI-assisted, business-owned |
| Deploy a Rule Change | Weeks (IT tickets + releases) | Minutes (author → test → publish) |
| Testing Before Go-Live | Manual or fragmented testing | In-UI simulation, CSV, shadow testing |
| Scorecard Management | Separate tools or spreadsheets | Built-in visual scorecard builder |
| Audit Trail | Limited or manual logging | 100% — every decision, timestamped |
| Data Sources | Custom integrations | 11+ pre-built connectors |
| AI Capabilities | None or bolted-on | Native AI recommendations and MCP |
| Multi-Tenant | Limited or absent | Entity-based isolation, multi-lender |
| Vendor Lock-In | Licensing dependencies | Zero — your rules, your control |
| Excel Compatibility | Limited support | Export, edit and re-import |
The Full Credit Lifecycle. One Unified Ecosystem.
ORIGINATE

AI + No-Code LOS
Capture leads, run KYC, build journeys. 7 AI agents.
DECIDE

AI-Powered BRE
Author rules in minutes.
Sub-100ms. Audit-ready.
MANAGE

Servicing & Lifecycle
Real-time servicing.
Multi-product. NPA-ready.
RECOVER

Agentic AI Recovery
Predict, engage, resolve. Autonomously at scale.
Is Your Decisioning Stack Ready for What's Next?
Each "yes" is a sign your current setup may be holding you back.
Select the statements that apply to your institution.
Your Next Credit Policy Could Be Live in Weeks
See how decision.ezee works with your credit policies, data sources and compliance requirements.
Case Studies News Blogs


Frequently Asked Questions
What are the operational trade-offs between cloud-based and on-premise credit decisioning deployments?
| Aspect | Cloud-Based | On-Premise |
|---|---|---|
| Integration Time | Cuts setup by 70% via APIs; no hardware waits. | Slower due to server provisioning and custom configs. |
| Upfront Costs | Low; subscription model, no CapEx on hardware. | High; servers, licenses, and IT infrastructure. |
| Scalability | Effortless peak handling during loan campaigns. | Limited; requires hardware expansion. |
| Maintenance | Vendor-managed updates and security patches. | Demands dedicated IT for upgrades and backups. |
How does automated underwriting within a decision engine differ from traditional scorecard-only approaches?
Automated underwriting uses real-time data APIs and ML models for dynamic risk assessment, unlike scorecards’ static point-in-time snapshots.
Aspect Automated Underwriting Traditional Scorecards
Risk Assessment Dynamic ML models adapt to patterns Fixed scorecard points
SME Application Verifies current cashflow instantly Relies on outdated docs, fraud risk
Decision Speed Minutes via automation Days with manual review
How does automated credit decisioning shorten loan approval timelines without increasing risk exposure?
Automated credit decisioning slashes TAT by 70% through real-time data pulls from bureaus like CIBIL during KYC. It flags anomalies instantly in personal loan apps, maintaining accuracy via audit trails. Lenders see approvals in minutes without added defaults.
In what ways can rule-based and AI-driven decisioning reduce loan defaults over time?
Rule-based and AI decisioning cut defaults up to 15% by blending CIBIL checks with predictive borrower health signals in SME underwriting. Over collections, AI monitors transaction spikes for early intervention. “AI-based scoring reduces default rates by up to 15%,” notes Forrester-linked analysis.
How do lenders evaluate credit decisioning platforms for accuracy, explainability, and regulatory fit?
Lenders prioritize explainable AI with auditable logic for fair lending audits alongside ≥95% decision accuracy on post-loan performance. They test real-time CIBIL integrations for bias-free outputs in high-volume personal loans. Platforms must log every rule for compliance evidence.
What criteria do small banks and credit unions use when shortlisting credit decisioning software?
Small banks shortlist credit decisioning software based on these key criteria:
- API speed for seamless core banking handoffs and instant TAT cuts.
- Scalability without adding staff, handling growth effortlessly.
- 19% automated decision adoption aligned with compliance needs.
- Configurable rules for secured loans, no heavy IT overhead.
- Focus on TAT reductions and instant member approvals.
What regulatory requirements should credit decisioning software support in highly supervised lending environments?
Software must enable human oversight, transparent outputs, and cybersecurity for high-risk AI like credit underwriting per EU AI Act Annex III. In India, it logs CIBIL-derived decisions for RBI audits during disbursal. Changes track by authorized users only for audit-proof history.
How is credit decisioning software typically integrated into core banking, LOS, and data infrastructure?
Decisioning integrates via secure APIs pulling real-time CIBIL and CKYC data into LOS workflows for instant underwriting. It hands off approved personal loans to core banking for disbursal, with CRM syncs for collections. Modern setups create interconnected ecosystems without code rewrites.
How do lenders configure credit decisioning rules differently across personal, SME, and secured loan products?
Lenders set lighter KYC rules for low-value personal loans, heavier cashflow analytics for SMEs, and collateral checks for secured via configurable scorecards. SME rules flag transaction volatility; secured prioritize asset valuation of APIs. No-code engines adapt without recoding.
Why is API-first architecture critical for modern credit decisioning and underwriting workflows?
API-first enables seamless real-time pulls from bureaus and core systems, automating end-to-end from application to disbursal. It supports peak volumes in digital lending without latency, unlike rigid legacy setups. This cuts manual exceptions to under 15% in practice.
